Homes may transfer to your beneficiaries without the need for a trust. However, in certain situations, a trust could help to avoid the probate process.
Editor's note:This post was originally published Augusty 25, 2020 and has been updated for accuracy, comprehensiveness and freshness on November 10, 2026.
Your home is probably the first thing you picture when you think about what your family inherits from you. If you’ve been through a long probate or watched a friend struggle to navigate one, it might sound like putting your home in a trust would make things easier for your family. In certain situations, it can be.
A trust is a specific mechanism that can help you transfer property without probate, but houses can also skip probate in other ways.
You don’t have to make these decisions alone. We’ll discuss whether you should put your home in a trust, or whether the simpler tools you already have cover what you need. And if you have more questions, a LegalShield® Personal Plan lets you get advice from a provider law firm for an affordable monthly fee.
Reasons to put your home in a trust
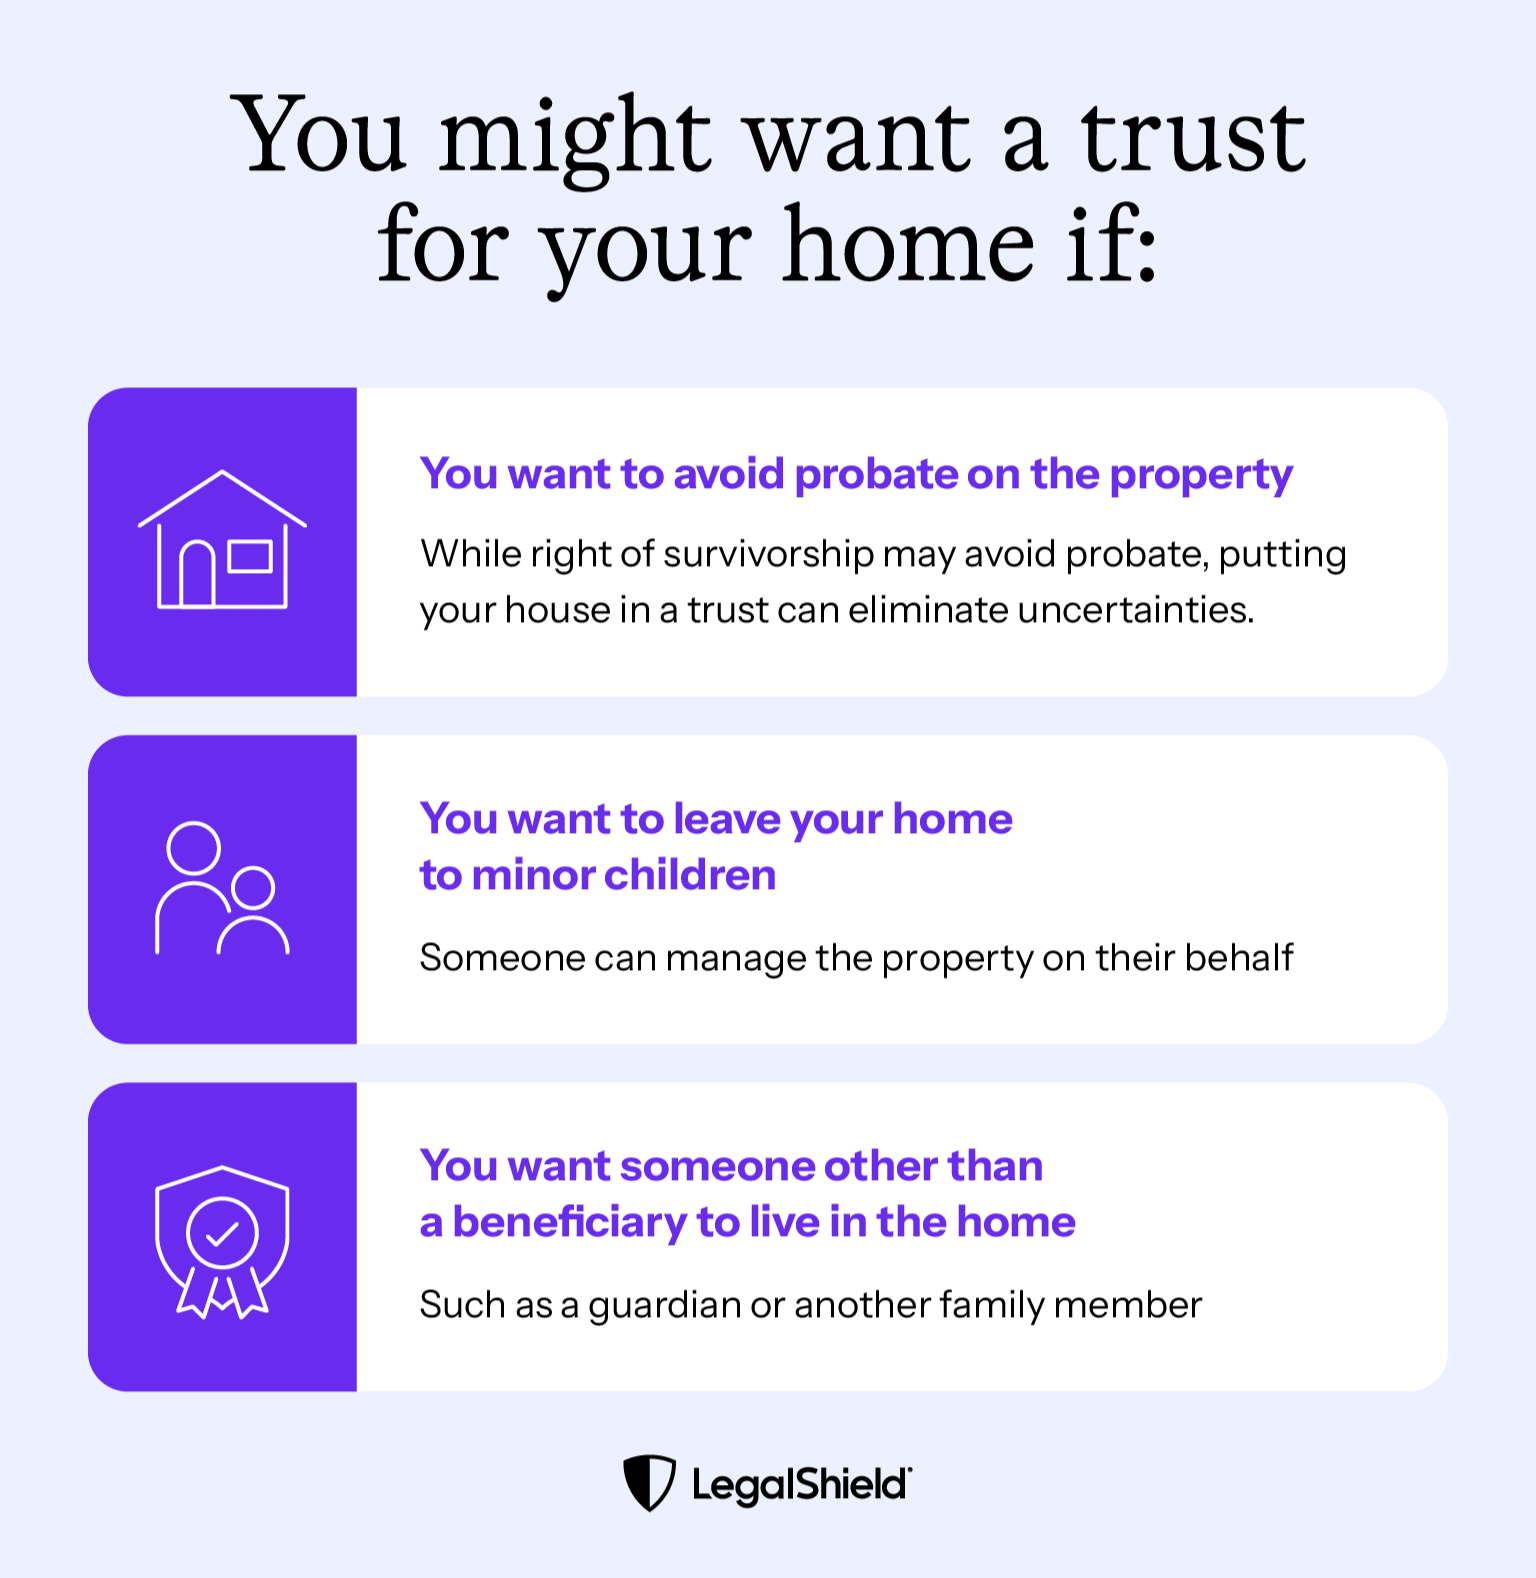
A trust is an arrangement where one person places their assets in the care of a third party on behalf of a beneficiary. The benefit of a trust is that it helps you control what will happen to your property even after you are gone. These situations might indicate when you need to put your home in a trust:
Reason 1: Avoiding probate
When your house sits in a trust, the terms you wrote decide what happens to it when you pass away, and it avoids probate.
This saves your family the time that probate takes, and potentially money, which you probably prefer goes to your beneficiaries instead of legal fees.
Reason 2: Married couples putting a home in a joint trust
If you jointly own a home with your spouse, you can also create a joint trust. You act as co-trustees during your lifetimes, and if one of you passes away or becomes incapacitated, the other becomes the sole trustee, and the trust itself is retained. This makes it easy to decide on your wishes together and create a resilient plan.
Reason 3: A beneficiary currently living in the home
Trusts can be good options when a specific person needs to stay in the home. Generally, you would need to address the property in your Trust if the other person in the home does not jointly own it with you. For example, this might be an adult child who moved back in, or a sibling who has been living with you.
Reason 4: Providing for children and guardians
If you have young children, you could include in your Trust to keep a home available to a guardian, granting the guardian the right to live in the home while still eventually passing the home to your children. Trusts allow you to decide on many details, like timing and triggering events, so you could leave assets to children that they get when reaching a specific age or completing certain conditions, such as graduating from college.
Putting property in a trust does require an extra step, though. You must retitle the deed into the trust's name so the trustee can act on it, which is one piece of funding a Trust.
Types of trusts that can hold real estate
Living Trusts come in two forms, revocable and irrevocable, and the difference is whether you can change your mind later. A Revocable Trust becomes irrevocable once the person or persons who created it dies. You can create a general trust that includes multiple assets, including your home, or you can create a trust just for the real estate.
Revocable Living Trust
When a trust is revocable, it technically owns the house, but you keep the power to rewrite the terms or end the arrangement. You can be your own trustee, which means you keep control of the trust during your lifetime.
You can live in the house, refinance it, sell it, or pull the property back out of the trust. Then, after you pass away, it moves the house to your beneficiaries without probate.
A Revocable Living Trust generally doesn’t fully separate the assets from you. There are circumstances in which you might want to separate the property from you, which would need a different kind of trust.
A LegalShield Provider Law Firm can set up a Revocable Living Trust for you, with a $250 fee, as part of the Premium Plan. At just $59.95 per month, members can put an estate plan in place without traditional hourly fees.
Irrevocable Trust
Irrevocable Trusts trade a loss of control for more protection. Once you create the trust, you might not be able to alter the terms. Selling or transferring the property become more complicated, as the Trustee who is usually a third party, controls the movement of assets in the Irrevocable Trust. This seems restrictive, but that’s exactly the point. The house stops being something you personally own, which can keep it away from certain claims from other parties.
Some people use Irrevocable Trusts to reduce estate taxes, protect assets from lawsuits, or plan for Medicaid. The level of protection you get and how well it works depend heavily on where you live. Speak to a lawyer familiar with your state’s rules to understand how they apply to your situation.
The pros and cons of putting your house in a trust
The strongest argument for a trust is that your house reaches the people you chose without a court process running first. The strongest argument against it is that you are paying for and maintaining a legal structure that a Will and a properly titled deed may already handle for your situation.
Pros
Cons
The house passes outside probate
Can be more expensive than other estate planning options
You set the terms and the timing
The deed must be retitled
A successor trustee can step in without a court
Needs updating as your assets change
Your family knows the plan in advance
Does not erase debts or liens on the property
House trust pros
One of the most desirable benefits of trusts is that the property inside them doesn’t go through probate. Your successor trustee works from the document you signed, which means your family won’t be waiting for court decisions.
A trust also applies during your lifetime if a time comes when you can’t manage things yourself. When a successor trustee is named in the document, they have standing to handle the property without a separate court proceeding.
Giving your loved ones clarity and making some decisions for them ahead of time is one of the biggest benefits you can get from a trust. If the pros of a trust appeal to you, you can learn more about how to put your house in a trust by reaching out to a LegalShield Provider Law Firm.
House trust cons
Trusts often cost more than Wills, and are more complicated, both to create and to keep current. You need to retitle assets and adjust the trust as needed to reflect changes in property ownership.
In terms of protecting your assets, trusts have limited usefulness. They can’t undo debts or liens. Irrevocable Trusts can potentially help reduce the taxable size of your estate, but this isn’t relevant for the majority of people. The standard estate tax exemption is $15 million for individuals and $30 million for couples.
Alternatives to trusts for your home
A trust may not be right for your situation, and often, homes pass to beneficiaries through other mechanisms. Let’s look at a broad overview of the other ways you can pass your property on to your loved ones:
Trust
Will
Right of survivorship
Gift
Holds title now.
Passes the house outside probate.
You can set terms.
Directs the house to a beneficiary at death.
Goes through probate.
Can be set up to pour into trusts or work alongside them.
When you own a home jointly with another person.
The house passes directly to the other person without the need for probate or a trust.
Overrides other estate tools like Wills.
Transfers ownership during your life.
Immediate and final
Tax implications
For many homeowners, a Will is enough. They’re powerful documents that direct where your assets go after you pass away. If you need more flexibility, they can contain instructions for setting up and managing trusts.
A trust set up inside a Will is called a Testamentary Trust, and it doesn’t come into effect until you pass away, so you don’t need to deal with retitling property now. If you want to learn more about complex Wills, get help with estate planning from a LegalShield Provider Law Firm.
Another option is to give the house away as a gift during your lifetime. If you do this, you give up all ownership rights as well as any say in how the property is used and who can inherit it. There can be tax considerations of giving a gift of this nature, including appraisals and gift tax. Talk to an accountant or lawyer before gifting your property.
As long as you co-own with the beneficiary, right of survivorship is the simplest option. It automatically passes your home to the person who co-owns it with you and overrides any other instructions there might be.
How a trust affects your mortgage, taxes, and selling your home
Trusts can potentially have impacts on you or your beneficiaries’ finances as they relate to the trust assets.
Mortgages
Some people are concerned about “due-on-sale” clauses in their mortgages. When the clause is triggered, the lender demands that the mortgage be fully paid off. Funding trusts and beneficiary transfers as part of trusts are generally exempt from these clauses thanks to a federal law, the Garn-St. Germain Act, as long as beneficiaries and occupants don’t change. This is only true of primary residences with some additional limitations. Even though exemptions are available, it is a good idea to talk to your lender before transferring your property.
If there is a mortgage on your property when you pass away, the beneficiary may be able to assume the mortgage, or they may have to refinance it, if the debt is still due. When preparing a trust, you can address how the trust can help the beneficiary with an outstanding mortgage.
Taxes and insurance
Anytime you’re making a change to real estate, it’s helpful to get advice from professionals; a Certified Public Accountant (CPA) and a lawyer can be a good start. Tax rules change depending on your location, the estate’s value, and other factors.
Funding a Revocable Living Trust with a house may not affect property taxes or the tax on the sale of the real estate. However, you may need to refile for homestead exemption and sometimes your county tax assessor may revisit your home’s value for the purpose of tax calculations when a new deed is filed.
It is also a good idea to contact your property insurance company and let them know you are transferring the property to a trust. Your insurance agent should add your trust as an additional insured. You may have to provide a copy of your trust or your Certificate of Trust so they can add it to your policy.
An Irrevocable Trust can be different. In some situations, with very high-value real estate, it may offer tax advantages. A property may lose homestead exemption when it is transferred to an Irrevocable Trust. Like the Revocable Living Trust transfer, the tax assessor may revisit an older assessment.
Selling your home
The trustee of a Revocable Living Trust often has the power to sell the asset. Usually, you would name yourself as the trustee with someone else as a successor trustee. In this case you would list and sell the house with the paperwork naming the trust rather than you, and you would sign as the trustee. If there are co-trustees, they will also need to sign. Be prepared to provide a copy of your trust to the closing company during the sale process.
An Irrevocable Trust permanently takes the home out of your control, and whether the trustee can sell it depends on the rules set up in the trust.
What happens to a home in a trust after you pass away?
What happens after you pass away depends on the wording of the trust. The trustee follows the directions in your trust about how to distribute the trust property, and your house is no exception.
The timing depends on what you specify in the trust document. Some trusts distribute within months. Others hold a home for years, releasing it when a beneficiary reaches an age you set or a condition you named is met.
Remember that debts and taxes tied to the property still get settled and are part of a trustee’s duties. It’s not a good idea to try and DIY a trust. You should have a lawyer walk you through the variables and options, and they can draft the right language.
Speak to a LegalShield Provider Law Firm and get your estate plan started
You undoubtedly have thoughts about who will inherit your property. The great thing about getting legal guidance on your estate decisions is that you don’t have to determine the best option yourself. You can say, “I want this to happen, and for these people to get these things.” With a LegalShield Personal Plan, provider lawyers can tell you what your options are and prepare them for you either as part of your membership plan or at a discounted rate.
Get Revocable Living Trust documents prepared for you by a provider lawyer for a $250 fee per person with the LegalShield Premium Plan. The premium plan is $59.95 per month.
Other plans start at $39.95 per month, and all include a Will, Living Will, and Power of Attorney prepared by a provider lawyer.
Create a plan for your home and family with a LegalShield Provider Law Firm at your side.
There’s no right age to create a trust. This decision depends on what you own and who depends on you. If you have people in your life who depend on you for a place to live, you may want to consider a trust to hold assets, including your real property.
When you transfer a residence into a Living Trust where you remain a beneficiary and occupancy does not change, it shouldn’t change the mortgage rates and payments. Confirm the transfer with your loan servicer beforehand, because you’re usually required to contact them with changes.
Whether you can sell a house in a trust depends on what the trust document says. A trustee's authority to sell comes from the document and from state law. You can write a Revocable Living Trust so that you can allow trustees to sell property from it and act as your own trustee. Before listing a property held in a trust, have a lawyer confirm the document gives you that authority.
Communications Director at LegalShield overseeing content creation designed to make legal protection simple and approachable. He focuses on offering straightforward, trustworthy guidance that empowers people to make informed decisions about their legal rights and responsibilities.
We’ll provide more information about the trustors vs. trustees comparison, what to consider when filling these roles, and how they work together in Revocable and Irrevocable Trusts.
A power of attorney with springing powers is a legal document that grants someone else the authority to act on your behalf only after a specific event occurs.
There’s no rule that says a lawyer has to set up your Trust for it to be valid. However, Trusts are complex and doing it yourself without a lawyer's help comes with risks.
A Certificate of Trust proves your Trust is real and names who can act for it, while your beneficiaries and assets stay private. It lets your Trustee handle Trust business, like opening accounts or transferring property.
A limited power of attorney often comes in handy when you need help for a short time or for a single purpose. This legal document can help in situations like when you’re traveling, serving in the military, caring for an aging parent, or sending a child to study abroad.
We’ll cover some of the most common scams, the red flags that give them away, how to protect yourself, and what to do if you’ve already been caught out.
An executor is responsible for ensuring your final wishes get carried out, so it’s important that you choose someone who is responsible and can bear the emotional burden.
An employer identification number is a nine-digit number the IRS uses to identify a taxpayer. The estate needs its own, and getting one is usually simpler than it sounds. Learn more about estate EINs.
•
5 min read
Thank you! You're subscribed!
Oops! Something went wrong while submitting the form.